Economy
OPINION: GCC Navigates Global Macro Volatility as Worldwide Growth Moderates to 2.6%
Against a backdrop where geopolitical developments have shaved an estimated 0.5 percentage points off global growth, moderating worldwide economic activity to 2.5% in 2026 before stabilizing at 2.6% in 2027.
GCC economies continue to demonstrate resilience through active trade flow rerouting and sustained non-oil momentum.
Coface has released its latest global Risk Review, revealing a multi-speed global economy contending with renewed inflationary pressures, elevated commodity prices, and tightening monetary conditions.
In its quarterly review, Coface carried out four country upgrades and three regional reassessments, alongside 20 sector adjustments worldwide. While global financial conditions tighten following policy rate hikes of 25 basis points by major central banks, regional enterprises are leveraging strong liquidity to navigate international supply chain adjustments.
Key Global & Regional Findings
- Global Growth Benchmark: World economic expansion is forecast at 2.5% in 2026 and 2.6% in 2027, impacted by higher commodity costs and elevated financing rates.
- Energy & Commodity Volatility: Hydrocarbon prices climbed with oil crossing the $100/barrel threshold in September, alongside significant gains in natural gas and agricultural commodities (+40% year-on-year for wheat).
- Monetary Tightening: Federal Reserve and European Central Bank rate hikes contributed to a 6% rise in the US dollar index and a 100+ bps climb in long-term borrowing rates globally.
- Regional Trade Agility: Despite complex maritime logistics, oil export volumes transiting through the Strait of Hormuz expanded significantly, accompanied by rapid commercial rerouting across secondary logistics corridors.
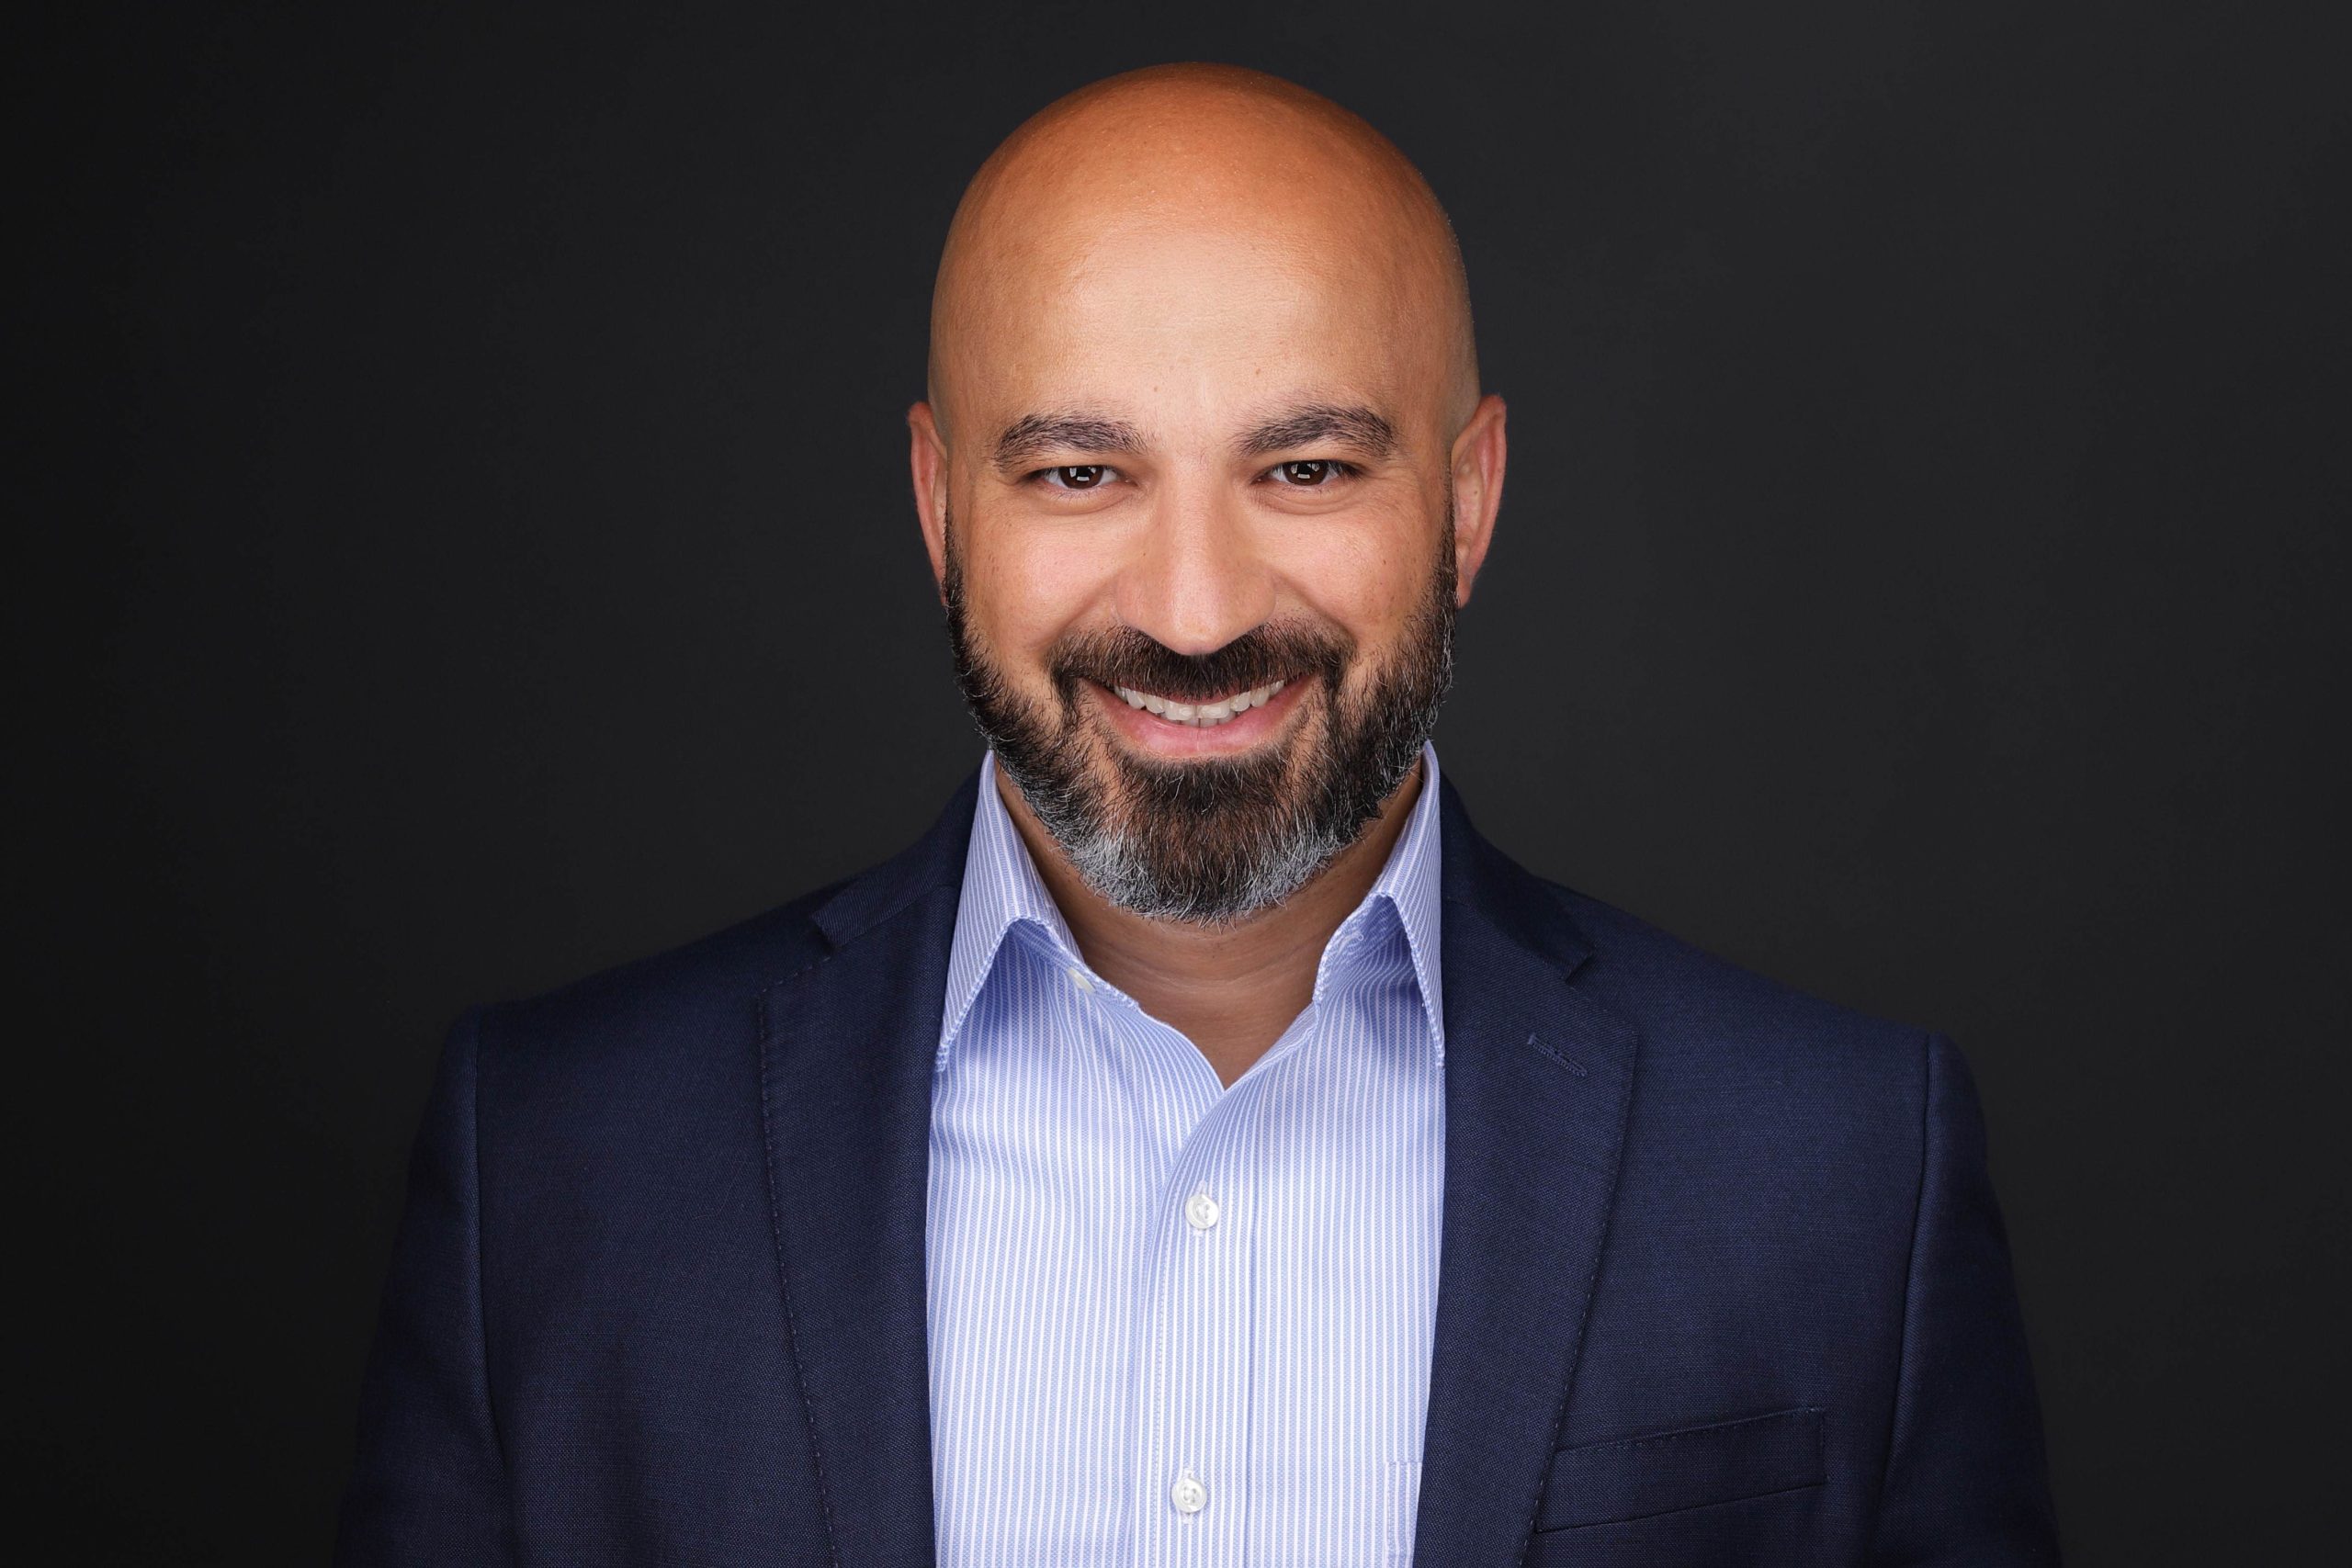
Mohamad Jomaa, CEO and Country Manager for GCC and Egypt at Coface, commented: “While the global economy contends with a prolonged cost-of-capital cycle and growth moderating to the 2.6% mark, the GCC continues to display significant domestic balance-sheet resilience.
“However, the global transmission of higher energy, freight, and agricultural import costs means regional businesses must avoid credit complacency. As global supply chains face renewed friction, the priority for GCC enterprises is proactive counterparty intelligence, insulating balance sheets against overseas supplier distress and securing multiple strategic options to support their operation.”
GCC Macroeconomic Focus: Managing Transit Agility and Import Security
Coface’s barometer notes that GCC economies are actively managing external friction originating outside regional borders. In response to short-term transit risks across primary maritime export routes, regional operators have demonstrated operational speed, expanding transshipment volumes and leveraging alternative logistics corridors. Coface’s updated quarterly assessments for Saudi Arabia, the UAE, and Qatar reflect these short-term logistical and transit cost pressures, while highlighting the underlying stability of the region’s fiscal and non-oil frameworks.
In the agri-food sector, Coface’s review highlights international supply lines as a strategic area for commercial monitoring. With global agricultural benchmarks impacted by extreme weather across European farming belts and logistical bottlenecks in Black Sea ports (+40% for wheat), the impact is on international import corridors rather than domestic structural factors. This dynamic reinforces the strategic importance of national food security programs, sovereign reserve storage, and source-market diversification currently underway across the Gulf.
A Multi-Speed Global Landscape
Across international markets, corporate risk trends diverge significantly:
- United States: Sustained economic resilience supported by consumer spending, full employment (4% unemployment rate), and capital investments in Artificial Intelligence infrastructure.
- Europe: Modest performance underpinned by resilience in Germany and Spain, though weighed down by rising insolvencies and public finance constraints.
- Asia: High-growth momentum in India (+7.5%) and Vietnam (+8.4%) driven by infrastructure development and AI hardware demand, contrasting with softer domestic consumption in China and energy cost pressures in Southeast Asia.
- Latin America & Africa: Persistent consumer inflation and margin compression driven by agricultural and transport price increases
Discover the full report here


OPINION: GCC Navigates Global Macro Volatility as Worldwide Growth Moderates to 2.6%

City Centre Muscat Celebrates 25 Years of Great Moments as Mall of Oman Marks Its Fifth Anniversary

HM The Sultan Accorded Official Reception Ceremony at Windsor Castle

61.7% of Middle Eastern Families Involve the Next Generation As Business Successors or Consultants

Future Fund Oman’s $5.2B Outlook: Where Will the Sultanate’s Next Big Businesses Come From?

Oman and the UK: From Historical Legacy of Over 220 Years to Future Partnership

Sohar International Launches Expatriate Banking Proposition with Housing Loans, Cashback, Insurance & Digital Remittance Solutions

INVESTIGATION: What Happens to Oman’s Economy at $60, $80, $100 and $120 Oil?

From Liverpool to Sultana: Testimonies to Centuries-Old Omani-British Friendship

What is El Nino – And How Is It Expected To Affect Oman’s Weather & Economy?

Power And Beyond: The Path To A Low-carbon Future

Al Mouj Muscat unveils Ghadeer Villas

Time to Buy Saudi Stocks? Some Investors Look at Dubai Instead

Hospitality Industry in Oman Estimated 90% Growth in 2022

Renewables are booming, but not fast enough to cap greenhouse emissions

Retail Abu Dhabi’s ‘Unbox Amazing’ generates sales of more than AED 2 billion in participating stores

Saudis Sign Deals From Energy to Metals in Bid to Salvage Forum

Saudi Arabia’s Gold Miner Plans to Be a Global Top-20 Supplier

Technology to drive Sultanate’s downstream industry

Digitization and Logistics Service Providers Can Help SMEs Make the Most of Peak Season Retail Trends

VIDEO: Building Oman’s Future – SAH’s Vision for Infrastructure, Innovation and Growth

VIDEO: Oman Cables Breaks Ground on OMR 10 Million-Plus Plant to Power Oman’s Industrial Future

VIDEO: Hitesh Akarte on Khimji Ramdas Infrastructure’s Role in Oman Vision 2040

Oman’s Hospitality Sector Enters a New Phase of Growth: Sadiq Al Matwani Al Lawati

Amr Baabood: Oman Climate Week Is About Moving From Climate Ambition to Climate Action

Mayan Al Asfoor on Leadership, Legacy and Empowering Omani Talent

LEADERSPEAK: Dhofar Insurance CEO Sunil Kohli on Oman’s Insurance Sector, Reinsurance & Market Outlook

VIDEO: Robert MacLean on how NHI is Shaping Oman’s Next Generation of Hospitality Leaders

The Future of Oman: Decoding The Sultanate of Oman’s Strategic Promotional Nation Brand

EXCLUSIVE: AI, Robotics & Wearable Sensors are Changing the Lives of Dementia Patients
-
 Artificial Intelligence1 month ago
Top 5 Interesting Things AI Did This Month – September 2026 Edition
-
 Fashion3 weeks ago
Luxury Watches That Could Appreciate Over the Next Decade [2026 Auction Buyer Guide]
-
 Economy3 weeks ago
OER Magazine September Edition 2026
-
 Banking & Finance1 month ago
The GCC’s 10 Richest Billionaires: Inside US$253.5 Billion of Wealth
-
 Magazines2 months ago
OER Magazine July Edition 2026
-
 Magazines2 months ago
Al Mar’a Magazine July 2026
-
 Banking & Finance1 month ago
INVESTIGATION: What If You Bought Apple Stock Every Time You Bought an iPhone?
-
 Alamaliktistaad Magazines2 months ago
Alam Al-Iktisaad Magazine July 2026 Edition