At equal pay, Muscat offers a stronger starting point for saving. Dubai can make financial sense too – but the salary premium, housing arrangement and employment benefits must justify the move.
An OMR 1,200 salary can produce two very different financial lives. In one, there is room for a private apartment, everyday spending and regular investment. In the other, the same income can feel considerably tighter once rent and recurring bills have been paid.
For someone choosing between Oman and Dubai, the useful question is how much remains after maintaining a realistic standard of living – and whether that surplus can grow over time.
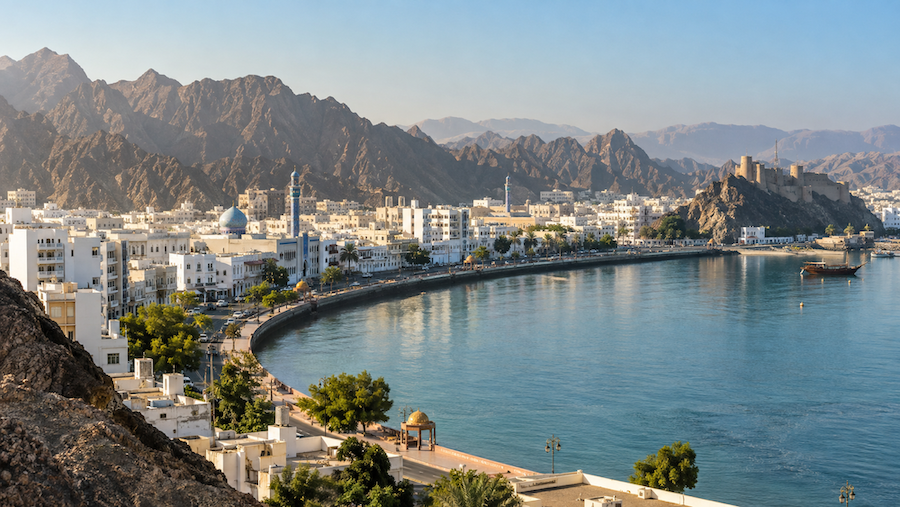
The evidence favours Muscat for a tenant earning the same amount in both places. However, it does not support a universal claim that everyone saves more in Oman. A Dubai employee with accommodation provided, a workable public-transport commute or a substantially better salary can reverse the result.
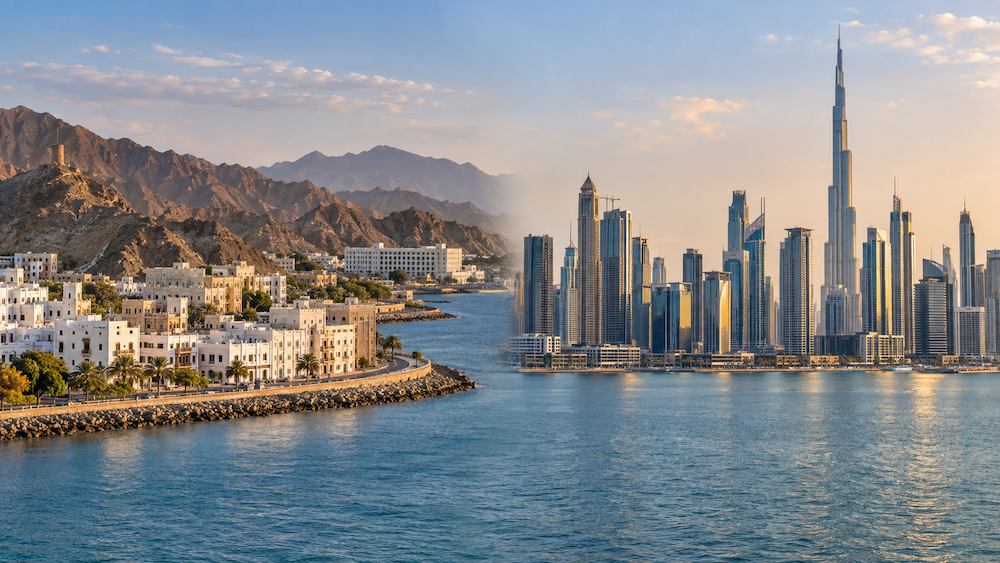
This OERLive comparison uses Muscat as the Oman benchmark and Dubai as the UAE benchmark. But our analysis does not treat Dubai as representative of the entire UAE, or Muscat as representative of every Omani city.
The Central Bank of Oman quotes a peg of US$2.6008 per rial, while the UAE central bank quotes AED3.6725 per dollar. That makes OMR1,200 approximately AED11,462, before conversion charges. The worked budgets below use the rounded rate of OMR1 to AED9.55, giving AED11,460.
For comparability, OMR1,200 means monthly spendable income after any payroll deductions, with cash allowances already included. Employer-paid accommodation or other benefits would be additional. Bonuses, debt repayments and remittances are excluded.
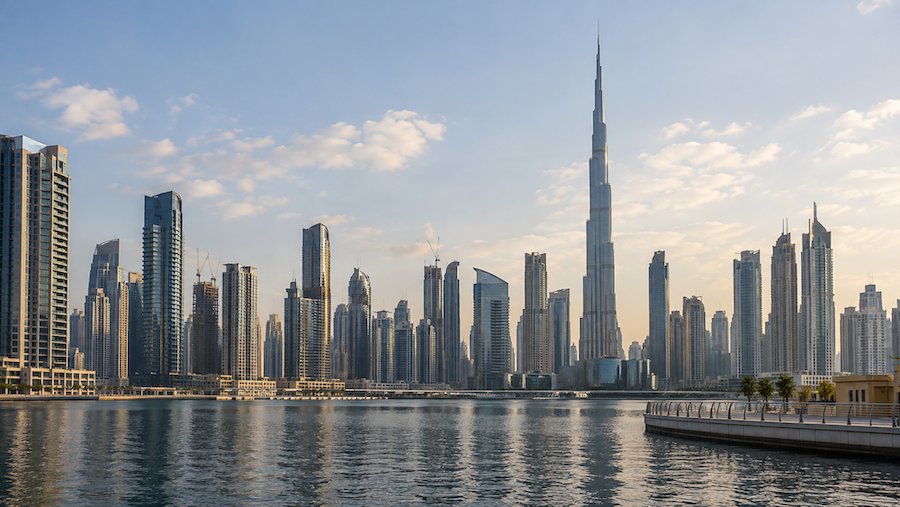
Housing creates the biggest divide: Dubai’s housing premium is visible even without using luxury districts. Bayut’s full-year 2025 report put advertised annual one-bedroom rents at AED68,000 in Deira, AED77,000 in Arjan and AED82,000 in Bur Dubai, albeit, these were asking-rent averages and not necessarily the amounts tenants ultimately paid.
At the comparison salary, Deira’s figure alone represents almost half of annual income. In Muscat, September 2026 listings reviewed on OpenSooq included an Al Khuwair one-bedroom apartment at OMR215 a month and furnished one-bedroom options around OMR250 to 270. These are advertised examples and not a citywide average or confirmation of current availability; some even include bills.
The properties are not identical in quality, size or commuting convenience. Nevertheless, they demonstrate why a modest private apartment can absorb a much smaller share of an OMR1,200 income in Muscat.
Premium Oman addresses require a different budget. Savills’ Q4 2025 review described broadly stable Muscat rents, while identifying Al Mouj as a location commanding a premium.
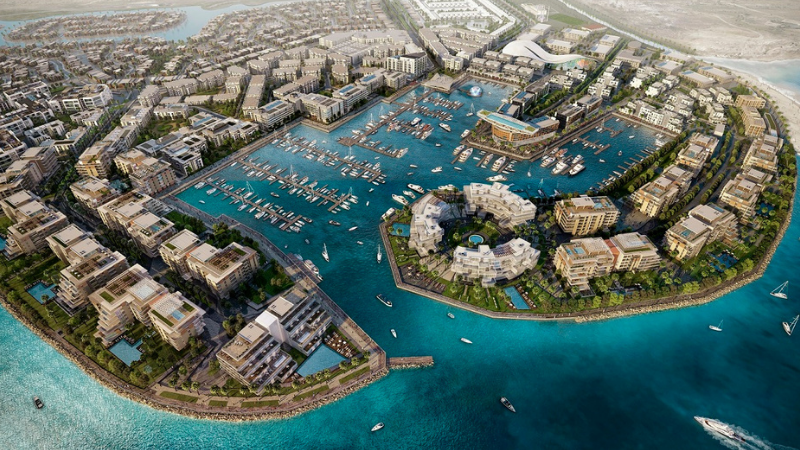
Al Mouj Muscat – A Premium Development in Oman
For a separate cross-check, Numbeo’s Dubai page, updated on September 22, 2026, reported a one-bedroom apartment outside the city centre at approximately AED5,507 a month, versus AED8,800 in the centre. Its figures are crowdsourced estimates, not official rental statistics.
Housing charges also matter, and Dubai Land Department states that tenants pay a municipality charge equal to 5% of annual rent, collected through the electricity bill. On an AED66,000 lease, that adds AED3,300 a year, or AED275 a month. Air-conditioning charges can require separate attention depending on the building.
To see what remains, consider a single working adult renting a modest one-bedroom apartment, cooking regularly and maintaining moderate discretionary spending. The Muscat case includes an economical existing car; the Dubai case uses public transport with occasional taxis.
These are editorial planning assumptions informed by rental evidence and official transport charges. They are not surveyed average household budgets, matched-property quotations or minimum living costs.
| Monthly allocation |
Muscat, OMR |
Dubai, AED |
Dubai, approximately in OMR |
| Rent |
280 |
5,500 |
576 |
| Housing/tenancy charges provision |
10 (if applicable) |
275 |
29 |
| Electricity and water |
55 |
650 |
68 |
| Mobile and home internet |
35 (baseline) |
450 |
47 |
| Groceries and household consumables |
130 |
1,100 |
115 |
| Dining and leisure |
60 |
500 |
52 |
| Transport |
120 |
550 |
58 |
| Personal spending |
40 |
400 |
42 |
| Provision for annual travel, medical co-payments and other irregular costs |
70 |
600 |
63 |
| Total spending and provisions |
800 |
10,025 |
1,050 |
| Income |
1,200 |
11,460 |
1,200 |
| Remaining for saving/investing |
400 |
1,435 |
150 |
Conversions are rounded. Dubai’s housing charge is calculated from the assumed rent. Muscat’s OMR10 is a contingency allowance, not a quoted statutory fee. All other allocations are assumptions, with applicable consumer taxes included.
The Muscat transport allowance covers fuel, maintenance, insurance, registration and a provision towards replacing an existing economical car. It excludes a new-car purchase or a car loan services on an EMI. Dubai’s allowance assumes the home and workplace are served adequately by public transport.
Employer-paid employee medical insurance is assumed in both cases. The irregular-cost provision is not an insurance quotation. Initial deposits, furniture and relocation expenses require separate capital.
The result is approximately OMR4,800 a year available to save in Muscat, compared with OMR1,800 in Dubai. That translates to roughly OMR3,000 a year of additional saving capacity under these assumptions.
Our model does not assume that every Dubai expense is higher though. Its grocery and transport allocations are lower than Muscat’s. Most of the difference actually comes from housing.
We’re also leaving room for variation: so, someone spending OMR200 more on rent, a car or leisure in Muscat would halve the modelled monthly surplus.
Dubai’s public transport is a meaningful financial advantage. RTA’s published 30-day Silver travel-pass prices are AED140 for one zone, AED230 for two zones and AED350 for all zones. Registered cards are required for these longer-duration passes. The all-zone price is approximately OMR37.
For a suitable commute, that can be considerably cheaper than the full cost of car ownership. A comparison that gives both residents cars and ignores Dubai’s public transport would miss an important way of controlling costs.
But lower rent is less helpful if the saving is consumed by taxis, a second vehicle or a difficult daily commute. Housing and transport should therefore be priced together.
The budget is sensitive to the apartment chosen. Reducing Dubai rent from AED5,500 to AED4,000, with the corresponding reduction in the 5% housing charge, would free AED1,575 a month – which is around OMR165. Holding everything else constant, saving capacity would rise from approximately OMR150 to OMR315. That is also a sensitivity calculation, not a claim that a suitable AED4,000 apartment is available for every commuter.
A Dubai offer needs to beat the savings gap. Using this budget, AED11,460 is currency-equivalent to OMR1,200 but produces less saving. To preserve the Muscat monthly saving of OMR400, equivalent to AED3,820, the Dubai worker would need:
- AED10,025 of spending + AED3,820 of saving = AED13,845 a month.
That is about 21% above the currency-equivalent salary, before allowing for relocation costs or a more expensive lifestyle. Preserving the same savings rate is a different test. The Muscat worker saves one-third of income and to save one-third in Dubai while spending AED10,025 requires approximately AED15,038 a month.
Neither figure is a universal relocation threshold – both are calculations from the stated scenario. Their value is the method: price the intended lifestyle, add the target saving and negotiate from that number. An AED15,000 offer would leave AED4,975 after this Dubai budget – approximately OMR521. At that point, Dubai would exceed the Muscat case’s OMR400 monthly saving, provided spending stayed unchanged.
Average salaries provide context, but require careful interpretation. OMR1,200 should not be treated as an average across either labour market. Job title, seniority, employer, benefits and workforce composition matter enormously.
Naukrigulf’s jobseeker-reported data provides some occupational reference points:
| Role |
Oman reported monthly average |
Dubai reported monthly average |
Dubai equivalent in OMR |
| Accountant |
OMR424 |
AED4,901 |
OMR513 |
| Senior accountant |
OMR687 |
AED8,068 |
OMR845 |
| Assistant manager |
OMR819 |
AED8,358 |
OMR875 |
Figures displayed when researched on September 22, 2026. Oman figures are national; Dubai figures are city-specific. These are platform sample averages, not official population averages or matched-worker comparisons. Benefit inclusion is not sufficiently standardised to treat them as equivalent total packages.
The accountant estimates drew on 390 Oman salaries and approximately 2,000 Dubai salaries. Different sources produce different results: Indeed reported an average Dubai accountant base salary of AED3,814, based on approximately 3,900 reported salaries and updated on September 14, 2026.
That divergence is a reason to avoid presenting one website’s number as the definitive market wage. It also shows why a Dubai job title does not automatically imply a large financial upgrade. For an actual move, a signed offer with a clear salary breakdown is more useful than a citywide average. Compare the same occupation, experience level and responsibilities, then value housing, insurance, transport and schooling separately.
This brings us to families, which require a completely different calculation. The single-person budget cannot be multiplied mechanically to represent a family. A couple can share rent and internet, while children may introduce larger housing needs, school fees, transport, childcare and dependent insurance.
School choice can change the result more than the country label suggests. Indian School Muscat’s March 11, 2026 circular set annual tuition for KG I to Standard VIII at OMR460 for 2026-27, payable across ten months.
The Indian High School’s Oud Metha campus in Dubai listed Grade 5 tuition of AED5,525 for 2026-27, plus an AED1,000 annual mandatory fee. Admission is also not granted by default in this particular institution. Some applicants may be subjected to a lucky draw system for admissions. But together, that is approximately OMR683, excluding supplies, transport and other applicable charges. New admissions also face a listed AED2,100 facility fee.
Again, these are specific school examples, not national averages or a judgement about educational equivalence. They show why a comparison based only on expensive international schools would exaggerate the burden for some households. Admission and seat availability must also be checked.
Dubai’s KHDA School Fees Fact Sheets allow parents to inspect mandatory and optional charges school by school. The correct comparison includes tuition, bus transport, books, uniforms and admission costs, with annual totals divided by 12 for budgeting.
Health cover deserves the same scrutiny. Dubai employers must insure employees, but dependent coverage should not be assumed. DHA guidance states that where the employer does not cover a spouse and dependants, arranging cover becomes the sponsor’s responsibility.
For a family earning OMR1,200 from one salary, Muscat’s cheaper housing can create useful breathing room. It does not make every school or housing choice affordable. But a second income or employer-funded education can change the comparison substantially.
Also, tax is not the deciding factor at this income yet. The UAE’s official government portal states that it does not levy personal income tax. Oman’s personal income tax law is scheduled to take effect at the beginning of 2028, with a 5% rate on taxable income for individuals whose relevant total annual income exceeds OMR42,000, subject to the law’s conditions.
An OMR1,200 monthly salary is OMR14,400 annually. On salary alone, it is below that threshold and it would therefore be misleading to deduct 5% from this Oman salary when comparing the two locations. Other income and the individual’s wider tax circumstances can require separate assessment.
Both jurisdictions have a standard VAT rate of 5%, although exemptions and zero-rating differ. Equal VAT rates do not make underlying prices equal, and VAT should not simply be added to every household budget line.
The first financial goal is resilience: a monthly surplus is valuable partly because it reduces dependence on debt when something goes wrong. Using six months of the model’s full spending and provisions as an illustrative buffer gives a target of OMR4,800 in Muscat and approximately OMR6,300 in Dubai. Saving the entire remaining surplus would take about 12 months in Muscat and 42 months in Dubai, starting from zero and ignoring interest.
This is not a mandatory emergency-fund formula. A needs-only reserve would exclude reducible spending; dependants, job uncertainty and relocation exposure could justify more.
Moving also requires cash before the first normal month begins. DEWA lists a refundable AED2,000 apartment utility deposit. Rent instalments, a landlord deposit, any brokerage charge and furniture must be budgeted according to the actual contract. Refundable deposits are tied-up cash rather than permanent consumption, but they still reduce immediately available savings.
Investing turns the monthly difference into a long-term difference. Living in Dubai is not a prerequisite for accessing international investments. Interactive Brokers (IBKR) lists both Oman and the UAE among its available countries, although account approval, products and the servicing entity depend on eligibility. Bank Muscat also offers domestic mutual funds, including a money market fund for short-term liquidity management.
The central investment question at this salary is how much can be contributed consistently after building a suitable cash reserve.
To illustrate the arithmetic, assume that the rounded monthly surpluses of OMR400 and OMR150 are invested for 15 years:
| Assumed annual return, compounded monthly |
OMR400 invested monthly |
OMR150 invested monthly |
Difference |
| 0% |
OMR72,000 |
OMR27,000 |
OMR45,000 |
| 4% |
OMR98,436 |
OMR36,914 |
OMR61,522 |
| 6% |
OMR116,327 |
OMR43,623 |
OMR72,704 |
| 8% |
OMR138,415 |
OMR51,906 |
OMR86,509 |
Illustrative calculations with end-of-month contributions, a zero starting balance and constant nominal returns. Figures are rounded. Returns are assumed net of costs and any applicable taxes; inflation is not deducted. These are scenarios, not forecasts, and actual investment values can fall.
The table above assumes a cash reserve has already been established and the same money cannot simultaneously fund that reserve and the investment portfolio.
Money needed for rent, emergencies or an imminent move has a different purpose from long-term investment capital. Investor.gov emphasises matching investments to time horizon and risk tolerance, and diversifying rather than relying on a narrow exposure. But diversification cannot eliminate market losses.
For modest monthly contributions, transfer charges, currency-conversion spreads and fund fees also matter. A hypothetical OMR5 charge consumes 10% of an OMR50 contribution before any return is earned. Compare the full cost of funding and holding an investment, rather than only its advertised trading commission.
For a single tenant receiving the same spendable salary and paying for accommodation, Muscat offers the stronger affordability case in this analysis. Lower housing commitments make it easier to build a buffer and invest regularly.
Dubai becomes more compelling when additional guaranteed pay or employer benefits more than cover the extra costs. Employer-provided accommodation, a convenient public-transport commute, a second household income or a credible route to substantially higher earnings can outweigh the initial cost disadvantage.
Career upside should still be distinguished from money already secured. A promotion that might materialise cannot pay this year’s rent. Compare the guaranteed package first and assess potential progression separately.
At OMR1,200, Muscat is more likely to leave a self-funding tenant with money to save. Dubai needs a better package – or a materially cheaper living arrangement – to match it. The financially better home is the one that produces a sustainable surplus after the life a household actually intends to live.
Research note: Researched September 22, 2026. Official sources establish exchange rates, charges, tax rules and transport prices; schools supply their own fee schedules. Rental reports, listings and salary platforms are identified by source and coverage. No comparable official median wage for the full Muscat and Dubai workforces was established in this research, so none is asserted. Budgets, savings thresholds and investment projections are illustrative calculations. Historical 2025 rental reports are not presented as September 2026 transaction data.



 Highlights1 month ago
 Magazines1 month ago
 Magazines1 month ago
 Banking & Finance2 months ago
 Alamaliktistaad Magazines1 month ago
 Magazines1 month ago
 Banking & Finance1 month ago