Banking & Finance
Central Bank of Oman Issues Regulatory Framework for Digital Banks
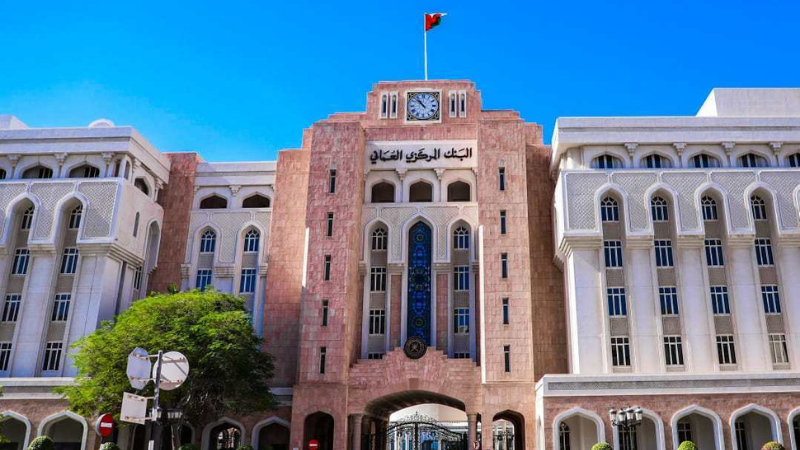
The Central Bank of Oman (CBO) has issued a regulatory framework for the licensing and supervision of digital banks, marking a major step toward modernising the country’s financial sector. The framework, which came into effect on June 1, 2025, is aligned with Oman Vision 2040.
The framework allows digital banks to operate as either locally incorporated joint-stock companies (SAOC or SAOG) or as branches of foreign banks, subject to regulatory approval in their home jurisdictions. Two types of licenses will be offered. Category 1 requires a minimum paid-up capital of RO30mn and allows full operations. Category 2 requires RO10mn but comes with business limitations, including caps on customer deposits and corporate lending, and a prohibition on proprietary trading. These limits are waived during the first two years of operation.
All digital banks must maintain a physical head or registered office in Oman. They may open administrative offices for customer support, but not traditional branches for transactions.
Shareholding limits apply: individuals and their affiliates may hold up to 15 percent of voting shares; corporate bodies up to 25 percent; and holding companies up to 35 percent. Cross-ownership in multiple banks is restricted to 15 percent.
Applicants must present a detailed five-year business plan covering digital services, target segments, profitability projections, and a financial inclusion strategy. The plan must outline IT architecture, cybersecurity readiness, and disaster recovery procedures. Digital banks are expected to adopt modern technologies such as AI, open banking, blockchain, and cloud computing. Omanisation targets start at 50 percent and rise to 90 per cent by year five.
The CBO mandates the submission of an exit plan alongside the license application. It must define conditions under which the bank would voluntarily cease operations, such as capital or profitability deterioration. The plan should address customer protection, risk triggers, and exit funding without regulatory assistance.
Licensed digital banks must comply with the Banking Law 02/2025, National Payment Systems Law 08/2018, and AML Law 30/2016. They are also subject to digital onboarding rules, cybersecurity frameworks, consumer protection regulations, and fraud prevention protocols. The CBO may require independent technical assessments at the applicant’s expense.
Non-compliance could trigger enforcement measures, including license revocation. The CBO reserves the right to reject incomplete applications or withdraw approvals if information is found to be inaccurate.


Apple’s Latest Earnings Highlight Strong iPhone Demand & Future Challenges

ahlibank Achieves Robust Q3 Results, Strengthening Market Position & Growth Outlook

Energy Oman Opens Category I Subscriptions for Sukuk Series 2

How Much Does It Cost to Buy at the World’s Leading Auction Houses?

A Look at the World’s Greatest Auction Houses & Their Record-Breaking Sales

The World’s Most Extraordinary Watches: What Makes Them Worth Millions?

Sohar International Signs 3 Strategic Agreements at Investment Partnerships Horizons Conference

Car Loan vs Cash: The Hidden Financial Advantage of Taking a Car Loan in Oman

Al Mouj Muscat Welcomes First Residents to Exclusive Jinan Island Community

Inside Binance’s $6.3 Billion Hack: How the Attack Unfolded and What Happens Next

Power And Beyond: The Path To A Low-carbon Future

Al Mouj Muscat unveils Ghadeer Villas

Time to Buy Saudi Stocks? Some Investors Look at Dubai Instead

Hospitality Industry in Oman Estimated 90% Growth in 2022

Renewables are booming, but not fast enough to cap greenhouse emissions

Retail Abu Dhabi’s ‘Unbox Amazing’ generates sales of more than AED 2 billion in participating stores

Saudis Sign Deals From Energy to Metals in Bid to Salvage Forum

Saudi Arabia’s Gold Miner Plans to Be a Global Top-20 Supplier

Technology to drive Sultanate’s downstream industry

Digitization and Logistics Service Providers Can Help SMEs Make the Most of Peak Season Retail Trends

VIDEO: Building Oman’s Future – SAH’s Vision for Infrastructure, Innovation and Growth

VIDEO: Oman Cables Breaks Ground on OMR 10 Million-Plus Plant to Power Oman’s Industrial Future

VIDEO: Hitesh Akarte on Khimji Ramdas Infrastructure’s Role in Oman Vision 2040

Oman’s Hospitality Sector Enters a New Phase of Growth: Sadiq Al Matwani Al Lawati

Amr Baabood: Oman Climate Week Is About Moving From Climate Ambition to Climate Action

Mayan Al Asfoor on Leadership, Legacy and Empowering Omani Talent

LEADERSPEAK: Dhofar Insurance CEO Sunil Kohli on Oman’s Insurance Sector, Reinsurance & Market Outlook

VIDEO: Robert MacLean on how NHI is Shaping Oman’s Next Generation of Hospitality Leaders

The Future of Oman: Decoding The Sultanate of Oman’s Strategic Promotional Nation Brand

EXCLUSIVE: AI, Robotics & Wearable Sensors are Changing the Lives of Dementia Patients
-
 Artificial Intelligence2 months ago
Top 5 Interesting Things AI Did This Month – September 2026 Edition
-
 Economy1 month ago
OER Magazine September Edition 2026
-
 Fashion1 month ago
Luxury Watches That Could Appreciate Over the Next Decade [2026 Auction Buyer Guide]
-
 Alamaliktistaad Magazines4 weeks ago
Alam Al-Iktisaad Magazine September 2026 Edition
-
 Banking & Finance2 months ago
The GCC’s 10 Richest Billionaires: Inside US$253.5 Billion of Wealth
-
 Banking & Finance2 months ago
INVESTIGATION: What If You Bought Apple Stock Every Time You Bought an iPhone?
-
 News2 months ago
OPEC+ Holds Output Steady for October as Focus Shifts to 2027 Quotas
-
 Artificial Intelligence1 month ago
What the World’s Top 10 Tech CEOs Really Earn