Economy
OPINION: Why Oman’s ESG Reporting is Being Tested Where Resilience, Carbon & Capital Meet
By Partha Das CCML, ESG Consultant at Crowe Oman
“The shipping route changes before the report does.”
By the time a business describes disruption in its annual sustainability report, a vessel may already have waited outside port, cargo may have missed its slot, an insurer may have repriced risk and an operations team may have chosen between a diesel generator and flaring gas to keep an installation safe. ESG reporting, for all its growing sophistication, still has a habit of arriving after the real story.
That is no longer good enough.
The regional conflict has collapsed what many companies once treated as separate workstreams into a single operating reality. Energy security, supply chain resilience, climate exposure, insurance and financial performance are now meeting in the same management meeting. Sooner or later, they will meet in the same ESG report.
The International Energy Agency’s October assessment captures the pressure. Gulf crude exports recovered strongly in September, reaching more than 75% of their prewar level. But renewed attacks on energy infrastructure and tanker traffic, record tanker rates and constrained refined product and LPG flows left that recovery exposed. The Strait may be only a passage of water, but it has become a test of how quickly risk can move through an economy.
Oil is only part of the story. In its November Global Gas Security Review, the International Energy Agency noted that disruption through the Strait of Hormuz had reduced LNG supplies from Qatar and the United Arab Emirates by more than 300 million cubic meters per day since March. Other producers have absorbed much of the shortfall, but the episode shows how quickly a regional security event can become a global gas and supply chain issue.
The timing could scarcely be worse. According to the Global Carbon Project’s 2025 Global Carbon Budget, fossil carbon dioxide emissions were projected to rise by 1.1% to a record 38.1 billion tonnes. At a moment when companies must keep energy and trade moving, the systems under greatest operational pressure remain central to the emissions challenge. That is an awkward detail, although not one that can be parked in a footnote.
The 2026 Global Sustainable Logistics Survey puts people behind the statistic. Based on the views of 1,085 logistics professionals in 64 countries, it estimates that logistics accounts for around 11% of global carbon dioxide emissions. More tellingly, 83% of respondents expected climate adaptation to require a fundamental redesign of logistics networks, while only 45% considered present efforts adequate. It is a global survey, not an Oman specific verdict. Yet its central tension should feel familiar here: logistics must reduce its own emissions while becoming more resilient to the disruption that climate and conflict are already creating.
That is the job now facing ESG reporting in Oman and the wider GCC: to explain the connection in terms that investors, lenders, regulators and boards can use.
The flare is visible. The accounting is less so.
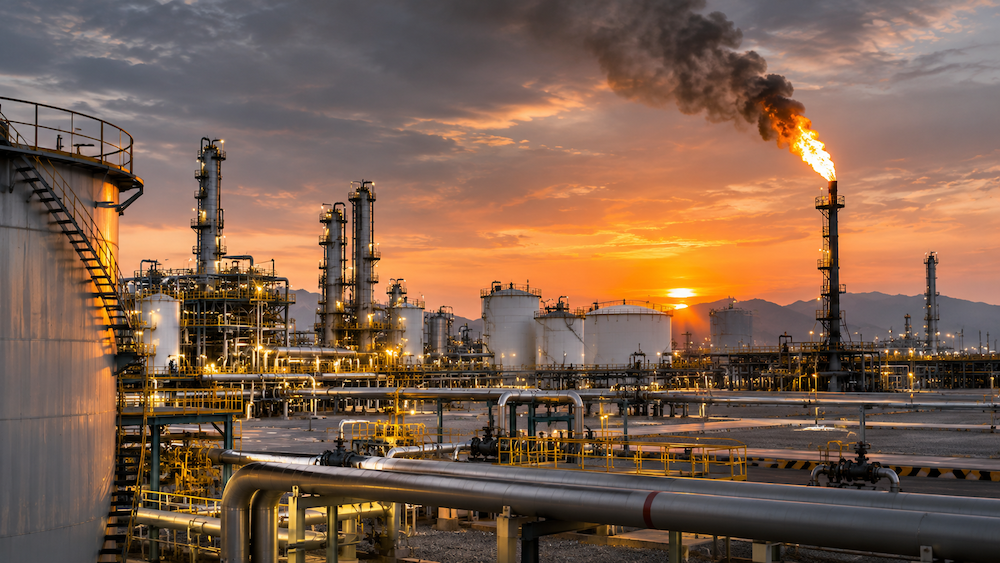
One early environmental signal from the conflict came from gas flaring. A Bloomberg analysis, citing satellite data from investigative consultancy Data Desk and subsequently reported by bne IntelliNews, estimated that the Das Island LNG facility in the United Arab Emirates flared gas equivalent to about 74,100 tonnes of carbon dioxide between 28 February and 22 March. Qatar’s Ras Laffan complex was estimated to have emitted roughly 101,300 tonnes of carbon dioxide equivalent over the same period.
The figures are striking, but they need professional restraint. Flaring during an infrastructure disruption is not automatic proof that an operator has abandoned its climate commitments. When gas cannot be processed, stored or exported safely, pressure must still be controlled and people and assets must still be protected. Burning excess gas is not a good climate outcome, but it may be the safer operational outcome.
This is where ESG reporting either earns its place or becomes decoration.
Flaring at a facility outside Oman is normally a Scope 1 emission of the operator that controls that facility. It does not automatically become an Omani company’s carbon footprint merely because the company has regional operations or buys goods and services from suppliers in the region. For an Omani company, the relevant question is whether the disruption changed its own operations or created material value chain emissions, such as longer transport routes, substitute air freight or altered inputs. Carbon accounting is not a game of regional guilt by association. Fortunately, it is slightly more disciplined than that.
So, what changed for the Omani company? Did an energy operator use emergency flaring, backup generators, fuel switching or altered plant utilization? That could affect Scope 1. Did a company shift its electricity source or rely more heavily on self-generation? That may affect Scope 2. Did goods travel further, wait longer or move through another mode of transport? That is likely to surface in Scope 3.
The GHG Protocol gives this analysis a structure. Transport purchased by a reporting company generally sits in Scope 3 Category 4. Downstream transport not purchased by the reporting company generally sits in Category 9. The classification follows the commercial arrangement, not whichever category happens to look tidier in a presentation.
That exercise cannot be built on a broad freight spend factor and a hopeful footnote. A credible estimate should record the route, distance, vessel or vehicle type, load factor, fuel data where available, port waiting time and methodology used. It should identify the disruption period separately and explain the uncertainty. If an abnormal event is quietly absorbed into an annual baseline, the company will later struggle to explain whether emissions rose because the business grew, operations became less efficient or geopolitics had a very expensive opinion about the supply chain.
The logistics survey helps explain why this matters. Route optimization and operational efficiency are widely adopted because they often reduce both cost and emissions. Low carbon fuels, fleet electrification and the infrastructure around them are judged effective but are moving more slowly because they need capital, policy support and shared infrastructure. The survey also identifies emissions calculation and reporting, sustainable transport knowledge and digital sustainability tools as critical but scarce skills. For Oman, the implication is practical: Scope 3 cannot be an annual request for supplier data and a last-minute calculation. It needs operational ownership throughout the year.
Oman’s businesses are already feeling the difference
In conversations with car dealers in Oman, I have heard a grounded version of the same story. Some have reported late arrivals of new vehicles, higher logistics costs and additional insurance charges connected with vehicle allocations. They relate these pressures to delayed shipping, rerouting and uncertainty in the region.
This is important, but it should not be exaggerated. A late vehicle does not automatically have a larger carbon footprint. A delay is first a commercial and operational problem; it does not necessarily mean a larger carbon footprint. The emissions effect arises when it leads to a longer route, vessel diversion, lower load efficiency, extended port waiting, additional handling or substitute air freight. That distinction matters because ESG reporting is supposed to make a company more honest about performance, not more imaginative about causation.
The survey also identifies road freight, sea freight and inland waterways as the most vulnerable network elements, with extreme heat the most pressing climate risk across transport modes and regions. For Oman, the immediate concern may be a marine disruption or a delayed vehicle shipment. The longer lesson is broader. A resilient logistics system needs to prepare for the pressure created by both geopolitical events and changing physical conditions, rather than assuming that one will politely wait for the other to finish.
Insurance offers another clue. The Financial Services Authority has introduced automatic cover for material damage to insured vehicles resulting from natural disasters and climatic events, including third party policies. The cost of that cover is aligned with expected risk. It would be careless to say that every driver now pays the same higher premium, but the direction is clear. Flood, cyclone and climate volatility are no longer occasional background events. They are moving into the price of protection.
For banks and insurers, this becomes a financial materiality question. Which borrowers are exposed to disrupted trade, higher fuel costs or delayed inventory? Could a delayed shipment affect working capital, repayment capacity or collateral value? How might climate related claims change underwriting assumptions? These are not sustainability questions sitting politely at the end of an annual report. They are credit, risk and capital questions.
Oman has achieved coverage. It now needs evidence.
Oman has made meaningful progress, and it should be said clearly. In the Crowe Oman ESG research report, my team reviewed the 2025 ESG disclosures of 89 listed companies. Every company completed the 30 Muscat Stock Exchange ESG metrics. 88% included comparative information from the prior year, compared with 54% in the first reporting cycle.
That change matters because comparative information is where reporting starts to earn its place. It allows an investor, lender or regulator to see movement over time, understand material variations and assess whether a company is improving or merely recycling last year’s narrative with fresher photographs.
The report also shows why the next stage is more demanding. While 97% of companies referenced GRI, only 24% disclosed quantified targets. External assurance was limited to 9%, and 89% of companies did not use a consolidated reporting boundary. These are not presentational gaps. A boundary that excludes subsidiaries, operating assets, joint ventures or material logistics activities can miss precisely where the operational, commercial and climate exposure sits.
“A target without a baseline, methodology, owner and evidence trail is a statement of intent. It is not yet a management tool.”
My colleagues and I presented the report at the Muscat Stock Exchange platform during Oman Climate Week 2026, hosted by the Environment Authority. The discussion with companies, investors and public sector stakeholders reinforced a simple view: Oman has created broad disclosure coverage. It now needs stronger controls, clearer boundaries, more quantified targets and data that can survive both investor scrutiny and operational disruption.
The FSA is asking a better question
The Financial Services Authority’s work on IFRS S1 and IFRS S2 matters because it moves the conversation beyond a list of ESG metrics. The FSA’s phased policy remains subject to feedback, but the Authority has stated that mandatory implementation is planned to begin on 1 January 2029. The message to entities within scope is already clear: build governance, data management and internal controls before the deadline starts looking uncomfortably close.
GRI has helped companies report the impacts of their operations; IFRS S1 and IFRS S2 ask them to explain how sustainability related risks and opportunities could affect the company’s prospects and enterprise value.
That is why IFRS S1 and IFRS S2 is not a license to produce a more polished sustainability brochure. They ask whether sustainability related risks and opportunities could reasonably affect cash flows, access to finance, cost of capital, financial position or financial performance.
The conflict makes a useful stress test. If a company faces fuel interruption, delayed cargo, higher insurance cost, restricted export access, energy price volatility or physical asset disruption, can it explain the financial pathway? Which contract is exposed? How long could disruption last? What happens to inventory, margin, capital expenditure, revenue and liquidity? Which emissions have changed, and are those changes temporary or structural?
A company that can answer those questions will be better prepared for IFRS S1 and IFRS S2. More importantly, it will be better prepared to run the business. Compliance is helpful. Knowing what is actually happening is better.
One region, several routes to compliance
The GCC is developing a common language for ESG reporting, although it does not yet have a single rulebook. The GCC Exchanges Committee introduced 29 shared ESG metrics in 2023, comprising 10 environmental, 10 social and 9 governance measures. They provide a useful regional base, but each market is moving at its own pace and through its own regulatory route.
Oman has achieved broad listed company coverage through the MSX metrics and is preparing for an ISSB based, financially material disclosure model. In the United Arab Emirates, Abu Dhabi Securities Exchange pairs mandatory sustainability reporting with 31 core indicators. Kuwait’s Capital Markets Authority requires Premier Market companies to disclose sustainability reports from 2026 for the 2025 financial year, while Boursa Kuwait’s latest guide incorporates IFRS S1 and IFRS S2. Saudi Exchange guidelines continue to build ESG disclosure into the capital market agenda.
Where does Oman stand? It is ahead in creating broad listed company disclosure coverage and in setting a clear direction towards international standards. It is still developing in the areas that determine whether disclosure becomes reliable: consolidated data, assurance, quantified targets, Scope 3 capability and connectivity with financial reporting. This is not an Omani problem alone. It is the region’s real work.
For groups operating across the GCC, the task is not another report. It is one data architecture. One operating fact must be capable of being mapped to GRI, MSX metrics, investor requests and IFRS sustainability disclosure without changing the underlying number. A company cannot maintain one emissions figure for a sustainability report, another for a lender and a third for financial risk disclosure without reconciliation. It can try, of course. Assurance teams tend to notice.
Reporting, capital and carbon markets are now tied together
Oman’s Ministry of Finance has provided an important link between sustainability, public policy and capital through its Sustainable Finance Framework. The framework enables green, social and sustainability bonds, sukuk and loans to finance projects with environmental or social benefit. It covers 14 eligible categories, including renewable energy, green hydrogen and ammonia, clean transport, water, energy efficiency, climate adaptation and social infrastructure.
Its real strength is what happens after issuance. The Ministry commits to annual allocation and impact reporting while sustainable finance instruments remain outstanding, supported by independent post issuance review. This is the discipline the wider market needs to understand. Sustainable finance is not a green label attached to a financing document. It is a promise about the use of money, the measurement of impact and the information investors receive afterwards.
Oman Climate Week 2026 brought this point into focus. Oman Net Zero Centre representatives described a pipeline of more than 200 emission reduction projects, at different stages from submission to development, as Oman prepares its carbon market. Oman’s updated national pathway targets a 33% reduction in emissions by 2035 below the 2024 baseline, with 7% unconditional and a further 26% conditional on international finance, technology and capacity.
At the Article 6 session, Oman Net Zero Centre representatives referred to three Article 6.2 activities, Khamilah, Al Multaqa and Barka, with a combined authorized mitigation volume of 804,323 tCO₂e. The national carbon registry, Meezan, is becoming part of the country’s infrastructure for carbon accounting and reporting.
The potential is significant. But carbon markets do not reward vague ambition for very long. They depend on clear project boundaries, credible baselines, additionality, monitoring, verification, transparent authorization and protection against double counting. They depend, in other words, on the same quality of data and governance that stronger corporate ESG reporting requires. The difference is that weak evidence carries a direct financial consequence.
The report must travel with the risk
Oman has a credible foundation: the MSX reporting cycle has created coverage, the FSA is directing the market towards globally recognized financial disclosure, the Ministry of Finance has connected sustainability priorities to sovereign finance, and the Oman Net Zero Centre is building a project and carbon market pipeline.
Now begins the harder work. Companies need to distinguish a normal operating variance from a conflict related emissions increase, a broad ESG statement from a financially material risk, and a delayed shipment from a value chain exposure that needs to be measured. They need to show where a number came from, who owns it, what changed and why.
The next annual report will reveal more than whether Oman has complied. It will show whether companies can follow risk as it travels from a flare to a shipping route, from a shipping route to an invoice, from an invoice to an insurance decision and ultimately to the balance sheet. If the number cannot make that journey with the risk, what exactly is the report preparing us for?
About the Author
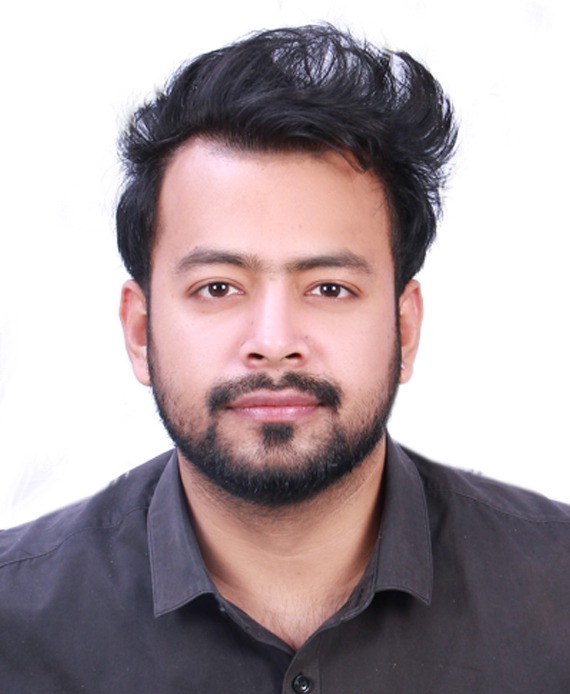
Parth Das is an ESG Consultant with a background in audit, accounting and finance. He advises SAOGs and public sector entities on ESG reporting, sustainability strategy, regulatory readiness and performance improvement, with experience across GRI and IFRS aligned disclosures. Parth holds a BSc in Accounting and Finance from the University of Bradford, the ICAEW Sustainability Certificate, the IFRS Learning and Assessment Program 2024 certification, and the Certified Carbon Management Leader credential.


OPINION: Why Oman’s ESG Reporting is Being Tested Where Resilience, Carbon & Capital Meet

The Rise of Oman in the World of High Perfumery

HH Sayyid Bilarab Bin Haitham Presides Over Official Unveiling of Al Yazan ITC in Wilayat Muttrah

Seven of the Most Expensive Homes Advertised in Oman

OER Magazine October Edition 2026

Apple’s Latest Earnings Highlight Strong iPhone Demand & Future Challenges

ahlibank Achieves Robust Q3 Results, Strengthening Market Position & Growth Outlook

Energy Oman Opens Category I Subscriptions for Sukuk Series 2

How Much Does It Cost to Buy at the World’s Leading Auction Houses?

A Look at the World’s Greatest Auction Houses & Their Record-Breaking Sales

Power And Beyond: The Path To A Low-carbon Future

Al Mouj Muscat unveils Ghadeer Villas

Time to Buy Saudi Stocks? Some Investors Look at Dubai Instead

Hospitality Industry in Oman Estimated 90% Growth in 2022

Renewables are booming, but not fast enough to cap greenhouse emissions

Retail Abu Dhabi’s ‘Unbox Amazing’ generates sales of more than AED 2 billion in participating stores

Saudis Sign Deals From Energy to Metals in Bid to Salvage Forum

Saudi Arabia’s Gold Miner Plans to Be a Global Top-20 Supplier

Technology to drive Sultanate’s downstream industry

Digitization and Logistics Service Providers Can Help SMEs Make the Most of Peak Season Retail Trends

VIDEO: Building Oman’s Future – SAH’s Vision for Infrastructure, Innovation and Growth

VIDEO: Oman Cables Breaks Ground on OMR 10 Million-Plus Plant to Power Oman’s Industrial Future

VIDEO: Hitesh Akarte on Khimji Ramdas Infrastructure’s Role in Oman Vision 2040

Oman’s Hospitality Sector Enters a New Phase of Growth: Sadiq Al Matwani Al Lawati

Amr Baabood: Oman Climate Week Is About Moving From Climate Ambition to Climate Action

Mayan Al Asfoor on Leadership, Legacy and Empowering Omani Talent

LEADERSPEAK: Dhofar Insurance CEO Sunil Kohli on Oman’s Insurance Sector, Reinsurance & Market Outlook

VIDEO: Robert MacLean on how NHI is Shaping Oman’s Next Generation of Hospitality Leaders

The Future of Oman: Decoding The Sultanate of Oman’s Strategic Promotional Nation Brand

EXCLUSIVE: AI, Robotics & Wearable Sensors are Changing the Lives of Dementia Patients
-
 Artificial Intelligence2 months ago
Top 5 Interesting Things AI Did This Month – September 2026 Edition
-
 Economy1 month ago
OER Magazine September Edition 2026
-
 Fashion1 month ago
Luxury Watches That Could Appreciate Over the Next Decade [2026 Auction Buyer Guide]
-
 Alamaliktistaad Magazines1 month ago
Alam Al-Iktisaad Magazine September 2026 Edition
-
 Artificial Intelligence2 months ago
What the World’s Top 10 Tech CEOs Really Earn
-
 Construction1 month ago
SAH wins double honours at Dossier Construction Awards & Summit 2026
-
 Featured2 months ago
OPINION: The Sultan Haitham City Residency Rule Most Buyers Don’t Know About
-
 Magazines2 months ago
OER Magazine August Edition 2026